Some 2026 tax moves close December 31. See yours in dollars before they do.
Preston's team looks at your whole money picture: your income, taxes, debt, accounts and goals. Within 7 days,CONFIRM you get a written plan to reach those goals sooner, with each move in dollars and the date to make it.
Early Black Friday price ends in
Your price
$1,997
Or about $166 a month, 0% interest
If your plan can't show at least $10,000 in value, you get a full refund.
 From Preston Seo, Legacy Investing Show
- 300+plans built
- $85,871in first-year financial impact shown in the typical planCONFIRM
- 97%of the 317 plans we checked showed $10,000 or moreCONFIRM
You earn good money. So why does it still feel tight?
You get the raise or the bonus, and a big piece of it is gone before it reaches your bank account. You earn more each year, and you pay more each year.
Most people only think about taxes in March. By then the year is over, and your CPA can only file what already happened.
Today it isn't too late. Some moves are open until December 31, and more are open until April 15. Your plan shows which ones fit you and what each one is worth.
If you plan in March
The year is over. The December 31 moves are closed, and you pay the bill as it stands.
If you plan this week
The December 31 moves are still open, and so are the April 15 ones. You have time to check each one with your CPA.
Your plan shows you what to do. Preston AI helps you do it.
Preston AI starts with the plan my team builds for you. When you need help with a step, you can ask a question using your plan and numbers instead of explaining everything again.
The 2027 Wealth Plan
This is the plan my team builds for members of our full 12-month program.CONFIRM This weekend you can get it on its own, without joining the program. It's 20+ pages,CONFIRM written from your numbers and your goals, and it covers tax, retirement, debt, investing, business setup and real estate in one place.
- Where you stand today: income, taxes, debt, accounts, and the tax rate on your next dollar
- What to do in the next 30 days, and the first question to ask
- Each move in dollars: when it works, and when it doesn't
- Your first-year value, as a low and a high estimate
- A month-by-month timeline, sorted by deadline
- The exact questions to bring your CPA, attorney, and adviser
12 months of Preston AI
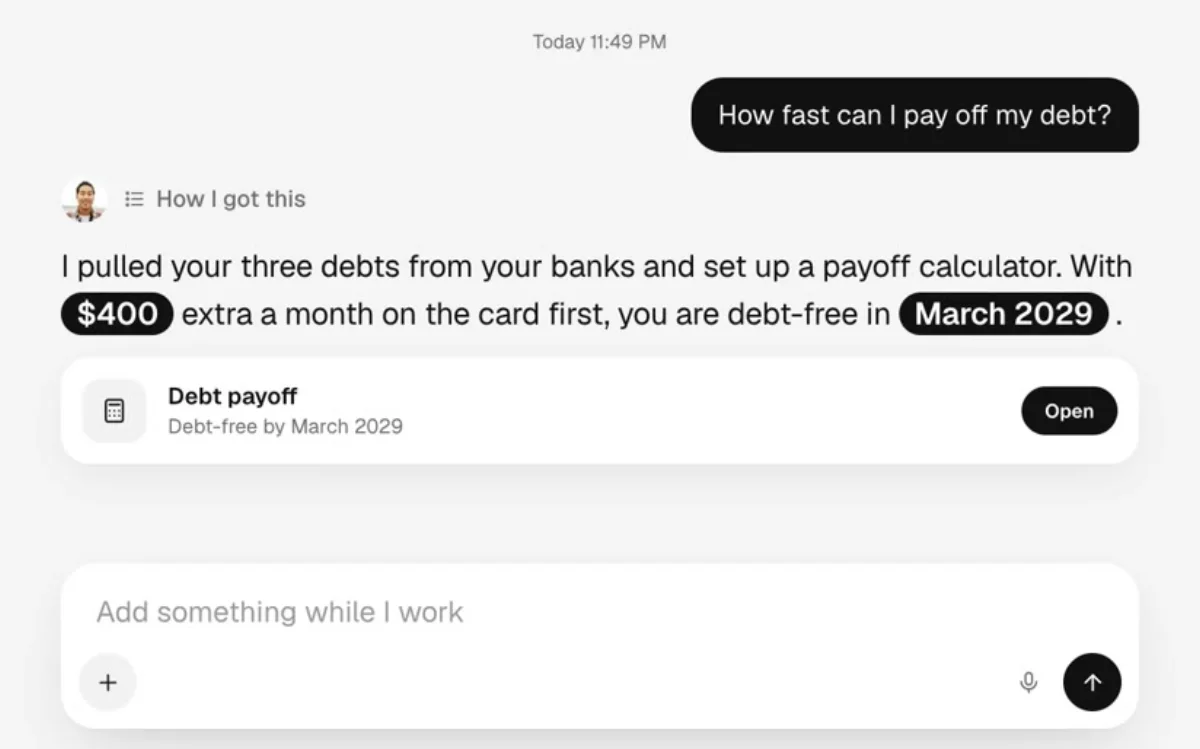
Your plan goes into Preston AI the day it's ready. From then on, it knows your numbers, your goals, and every move in your plan. It turns your plan into steps and helps you finish each one.
- Answers about your life, not someone else's. Ask anything. It answers with your plan, your tax rate, and your accounts in mind.
- It remembers you. Tell it once about a raise, a new baby, or a new house. It can use what you've already shared when you ask your next question.
- It sees your real money, if you let it. Connect your bank and investment accounts, and it answers with your real balances.CONFIRM
- You always know the next step. Each one shows when to do it, what it's worth, and what to ask your CPA.
It only reads your accounts. It can't move money. We never sell your data. Your bank login goes to Plaid, never to us.
Example data
You get both for $1,997, or about $166 a month for 12 months. The price ends Monday, November 16 at 11:59 PM ET.
Get my plan for $1,997Your plan arrives five weeks before December 31.
Order by Monday, November 16 and your plan reaches you by November 23.CONFIRM That leaves you time to talk to your CPA and make the year-end moves.
- Sale weekend$1,997 for the plan and a year of Preston AI.
- Your plan arrivesJoin this weekend. Have your plan by Nov 23.
- First deadline 401(k) paychecks, Roth conversions, kids' wages, rental write-offs.
- Last 2026 estimate dueAsk your CPA if you need it.
- Your first 2027 paycheckSet your W-4 and 401(k) for 2027 from day one.
- S-corp election for 2027For business owners whose profit keeps growing.
- Second deadline 2026 IRA and HSA contributions, and your individual 2026 return. SEPs follow your business's filing deadline.
Ten moves from real client plans. Each one has a deadline.
Each one came out of a real client's plan, with the dollars their plan projects and the date it closes. Ten is only a sample. Your plan has its own list, built from your numbers.
Which of these fit your return, and what are they worth to you? Your plan shows you.
Get my plan for $1,997300+ plans built. The typical plan shows $85,871 in first-year financial impact.
That's the plan's own estimate across taxes, debt, cash flow, and investing.CONFIRM Here are seven real starting points. The core plan leaves real estate out. If property fits you, the next column shows how far it can go.
| Starting point | Core plan, projected | If real estate fits, projected | What drove it |
|---|---|---|---|
| Two incomes, retirement and real estate on the table | $155,264 | $459,973 | Retirement, a Roth conversion plan, cost segregation, both spouses on one plan |
| Household with cash and a spouse starting a business | $119,036 | $489,424 | The spouse's consulting business, investing, a path to a first rental |
| High-income household, age 60 to 63 | $113,379 | $939,433 | Super catch-up, short-term rental, cost segregation, more cash put to work |
| Business owner looking at a second property | $103,587 | $436,215 | A single-member LLC, retirement through the business, cash flow first |
| Tax, business, investing, and property all in play | $73,363 | $445,650 | Real estate, retirement, entity setup, and investing working together |
| Early on, with less to invest right now | $36,726 | $41,970 | Tax cleanup, smarter investing, and an order that fits today |
| Rebuilding income and savings from scratch | $11,653 | $166,205 | An LLC, a growing income, dependent credits, and the right debt order |
Three W-2 earners, and what their plans show.
- $23,000projected tax savings
Lauren earns $125,000 on a W-2 and already had a good CPA. Her plan found 7 strategies worth about $23,000 in projected tax savings.CONFIRM
- $72,799 to $79,022projected first-year impact
Kevin works a W-2 job at a bank. His plan lays out 7 tax strategies and a W-4 fix, plus $34,800 a year going into his 401(k), HSA and Roth.CONFIRM
- $92,000 to $127,000projected year-one benefit
Trent earns his income on a W-2. His plan shows $92,000 to $127,000 in projected year-one benefit.CONFIRM
It completely changed the way I think about my taxes and my credit. Getting my bookkeeping set up made tax season so much easier, and it's the reason I finally opened custodial investment accounts for my kids. Now I actually know what I'm working toward: clearing the credit cards and building our emergency fund.
Your plan shows the same kind of numbers for your household. If it can't show at least $10,000 in value, you get a full refund.
Get my plan for $1,997This plan is for people who do the work.
It fits best if you earn $100K or more from a job, a business, or both, and your tax bill feels high and random. You want tax, debt, retirement, and real estate considered in one plan. And you're ready to move before these deadlines.
Skip it if you want someone to file your taxes, or you want a guaranteed return. And skip it if $1,997 would go on a card you can't pay off this month.
Want a team with you all year?
Live coaching and a dedicated Wealth Guide are part of our full program, not this offer. If you join it later, everything you pay here counts toward it.
One year I earned about $500,000. My federal refund that year was $46.
I started where you might be today, with a W-2 and a six-figure sales job. I bought my first rental while I still worked there, and I learned taxes, investing, and real estate the slow way. We were financially free by 28, and I left my job at 30. Since then, we've built a real estate portfolio worth more than $15 million. And I've gone through more than 1,000 tax returns.
Today my wife Bridget and I spend most of our days with our boys. I think money is for living your life while you can still enjoy it, and I don't think you should have to wait until you're 60.CONFIRM
Your plan is what I look for, put on paper by my team, with your numbers on it. Order this weekend, and you'll have your plan before December 31. April 15 is still ahead.
Preston Seo, Legacy Investing Show
$1,997 for the plan and a year of Preston AI.
Order by Monday, November 16 at 11:59 PM ET. CPA firms that sell a one-time tax planning package charge $1,495 to $7,500 for it.CONFIRM Your plan also covers retirement, debt, investing and real estate, and it comes with a year of Preston AI.
- Order today. You get the questionnaire by email right away.
- Fill out your questionnaire. Tell us about your money and what changed this year, like a new job, a bonus, a business, a sale or a retirement date. Upload your latest filed return if you have one.
- Get your plan within 7 days of joining.CONFIRM
- Open Preston AI and work through it step by step.CONFIRM
Want to talk it through with someone? At checkout, you can add a 1-on-1 call to walk through your plan for $300.
2027 Wealth PlanCONFIRM
$1,997
One payment, or 12 monthly payments of about $166 with Splitit. Same $1,997, 0% interest.
- Your 2027 Wealth Plan, built from your numbers within 7 days
- 12 months of Preston AI, loaded with your plan
- Every move in dollars, sorted by deadline
- Your first 30 days mapped week by week, with the questions to bring your CPACONFIRM
- Everything you pay counts toward the full program if you join later
- At least $10,000 in value in your plan, or a full refund
This sale has ended.
At least $10,000 in value, or your money back.
That's 5 times what you pay. If your plan comes in under $10,000, email us within 30 days of getting it for a full refund. You won't have to argue your case.CONFIRM
Value is your plan's own first-year estimate of three things:
- Tax you won't pay
- Your own money back in your paychecks sooner
- Money moved into tax-free or tax-deferred accounts
Moves that only apply later don't count. We checked 317 of our plans, and counted this way, 97% showed at least $10,000.CONFIRM
Questions people ask before they buy.
Is it too late to make a difference for 2026?
No. Your 2026 return isn't filed yet. A few moves close December 31, like your last 401(k) paychecks or a Roth conversion. Many stay open until April 15, 2027, like 2026 IRA and HSA contributions. SEP contributions follow your business's filing deadline, including extensions. Your plan sorts each move by its date, and anything too late for 2026 goes into your 2027 steps.
Can I pay monthly?
Yes. Choose 12 monthly payments at checkout and pay with Splitit: about $166 a month on your credit card, 0% interest, $1,997 total. Splitit needs a personal credit card and a billing address in the US, Canada, the UK, the EU, Australia or a few other countries.
What if my plan shows less than $10,000?
Then you get a full refund. Email us within 30 days of getting your plan, and you won't have to argue your case. The guarantee covers both ways to pay.CONFIRM
What do I have to send?
After you order, you get a questionnaire by email. It asks about your income, accounts, debt, business, property and what changed this year. Upload your latest filed return through the secure link if you have one. If it isn't filed yet, upload the one before it, or just answer the questionnaire, and your plan is built from your answers. Please don't email your return to us.CONFIRM
I already max out my 401(k). Is this still worth it?
Yes. A full 401(k) is one move. Your plan looks at the rest: a backdoor Roth, an HSA, your withholding, business setup, and real estate if it fits. And if your plan can't show you at least $10,000 in value, you get your money back.
I only have a W-2 job. Will my plan find anything?
Yes. Lauren earns $125,000 on a W-2 and already had a good CPA, and her plan found 7 strategies worth about $23,000 in projected tax savings. If a side business would help you, your plan says so and suggests what kind could fit.CONFIRM If you never start one, your plan still shows what you can do with your paycheck, your retirement accounts and your debt.
I'm close to retirement. Is this for me?
Yes, if you still have taxable income and pre-tax retirement money. Your plan looks at Roth conversions, including how much to move each year before required minimum distributions start and how that changes your tax bracket, and your CPA has the final say.CONFIRM
My spouse needs to see this first.
That makes sense, because most of our plans are for couples. Your plan covers your household, with both incomes, both sets of accounts and one list of dates, and you can fill out the questionnaire together after you order.CONFIRM
Why is it called a 2027 plan?
Because it covers both years. It helps you finish 2026 before April 15. Then it sets up all of 2027, starting with your first paycheck in January.
Is the plan written for me, or is it a template?
It's written from your answers about what changed this year, like a layoff, a bonus, a new business, a sale or a retirement date, and from your return if you send one. The examples above show different starting points, strategies and projected values. Your plan uses your own information.
Am I talking to Preston when I use Preston AI?
No. Preston AI is an AI, not Preston, and not a licensed advisor. It answers from Preston's teaching, your plan, and your own numbers. The plan itself comes from Preston's team, and the app works from it.
Is my bank data safe?
Connecting accounts is optional. If you do, it only reads your accounts. It can't move money. We never sell your data. Your bank login goes to Plaid, never to us.
Can't my CPA just do this?
You don't have to change CPAs. Most CPAs are paid to file last year's return, and planning next year usually isn't their job. Your plan gives you a list of moves to put in front of your CPA, with the dollars and the dates, so the two of you can decide what to do before the deadlines. Your CPA has the final say on every move.
Do you file my taxes?
No. We don't prepare or file returns, so your CPA or your tax software still does that. Your plan gives you the moves, the dates and the questions to bring your CPA, so you can act before you file.
Is Preston a CPA?
No. In his words, "I'm not a CPA or a licensed advisor." He started as a W-2 earner in a six-figure sales job. Since then, he has gone through more than 1,000 tax returns and built a real estate portfolio worth more than $15 million. Your CPA files your return, and your plan looks ahead, so you can bring your CPA the moves before the year closes.
Who sees my tax return?
Only the team that builds your plan sees your return. You upload it through a secure link, it's kept private and protected, and we never sell your data.CONFIRM
Is this just tax advice?
No. Your plan looks at tax, retirement, business setup, cash flow, debt, investing and real estate together. The money usually shows up in how those pieces fit, more than in any single move.
Do I have to buy real estate?
No. The core plan numbers above leave real estate out. They come from moves like retirement accounts, withholding, debt order, HSAs, and business setup. If property doesn't fit you yet, your plan says so.
Is this the full Legacy Wealth Blueprint?
No. You get your plan and 12 months of Preston AI, and the full program adds coaching, a Wealth Guide, the community, a prior-year return review, a CPA brief and our partner network. If you talked to our team about the full program and the timing wasn't right, this is a way to start with your plan, and everything you pay here counts toward the program if you join later.CONFIRM
What happens after November 16?
The $1,997 price ends at 11:59 PM ET that Monday, and the order page closes.CONFIRM
Order by Monday, November 16. Your plan arrives before the first deadline.
Get my plan for $1,997Or about $166 a month for 12 months, 0% interest· At least $10,000 in value, or your money back.